
Introduction
Discovering that your financial information may be compromised can be overwhelming. Whether it's a stolen credit card number, a data breach leak, or compromised banking credentials, quick and methodical action can significantly reduce damage and help you regain control of your finances.
The key is to act without panic and follow a systematic checklist: secure access, halt fraudulent transactions, document evidence, freeze credit lines, and set up robust monitoring for the future. Use the following seven-step checklist as an immediate response plan.
Step 1: Secure Your Accounts Immediately
The moment you suspect your information has been leaked or accessed without authorization, your top priority is locking out intruder access.
- Change Primary Passwords: Create complex, unique passwords for online banking, credit card portals, investment accounts, and payment apps.
- Secure Your Primary Email First: Password recovery links are sent to your email. If your email is compromised, hackers can reset all other account passwords.
- Enable Multi-Factor Authentication (MFA): Set up two-factor authentication using authenticator apps rather than SMS where possible.
"Prioritize securing your primary email inbox immediately. Hackers who gain access to your email can intercept password resets for almost every financial institution you use."
Step 2: Contact Your Bank & Card Issuers
Call the customer service or fraud departments of your bank and credit card providers immediately.
- Block & Reissue Cards: Ask representatives to cancel compromised cards and issue new account numbers and cards.
- Place Temporary Account Locks: Request temporary restriction while security resets occur if online banking was compromised.
- Document Customer Service Calls: Keep a record of representative names, dates, times, and confirmation or case numbers for follow-up.
Step 3: Freeze Credit Reports
Placing a credit freeze prevents lenders from accessing your credit report to open new accounts in your name. Freezing your credit is free and does not affect your credit score.
Major Credit Bureaus to Contact
- Equifax: Freeze online at Equifax.com or call 1-800-685-1111.
- Experian: Freeze online at Experian.com or call 1-888-397-3742.
- TransUnion: Freeze online at TransUnion.com or call 1-888-909-8872.
You can also place a Fraud Alert with any one bureau, which mandates that businesses verify your identity before extending new credit.
Step 4: Review Transactions & Dispute Fraud
Thoroughly inspect bank statements, credit card ledgers, and digital wallet history line-by-line for recent months. Look out for small initial test charges (often under $5) used by scammers to verify active cards.
- File Formal Written Disputes: Submit charge disputes directly through your online banking dashboard or customer service portal.
- Maintain a Documentation Folder: Keep screenshots, dispute reference numbers, email confirmations, and bank correspondence in one place.
Step 5: File Official Reports & Alerts
Official government and law enforcement reports provide crucial legal documentation when proving identity theft and resolving fraudulent debts.
- FTC Identity Theft Report: File an official report at IdentityTheft.gov to receive a personalized recovery plan.
- Local Police Report: File a report with local law enforcement if significant financial theft or impersonation has occurred.
- IRS Fraud Alert: If your Social Security number was exposed, notify the IRS to prevent fraudulent tax filing under your SSN.
Step 6: Protect Devices & Digital Access
Ensure malware, keyloggers, or malicious browser extensions on your personal computer or mobile phone are not continuously leaking sensitive credentials.
- Run Antivirus & Antimalware Scans: Perform deep system scans on all computers and mobile devices.
- Update Operating Systems: Keep OS, browsers, and security software updated to patch known vulnerabilities.
- Avoid Public Wi-Fi Networks: Never access online banking or sensitive accounts over unencrypted public networks without a secure VPN.
Step 7: Build Long-Term Monitoring Habits
Recovering from compromised financial information requires transitioning from emergency response to sustained security habits.
- Set Instant Transaction Alerts: Enable real-time SMS or push notifications for any debit or credit transaction above $0.
- Review Annual Credit Reports: Order free credit reports regularly via AnnualCreditReport.com.
- Consider Credit & Identity Monitoring: Use reputable identity monitoring services if your risk profile remains high.
Need Help Managing Financial Risk & Recovering?
Our team can help you build safer money systems, recover from fraud stress, and protect your long-term financial stability.
Conclusion
Having your financial information compromised is stressful, but taking structured, immediate action dramatically minimizes potential losses and protects your credit standing.
By securing your digital credentials, working closely with financial institutions, freezing credit reports, and building long-term monitoring routines, you take full control of your financial safety and peace of mind.
Recent & Important Articles
 Credit & Safety
Credit Card Late Payments: Consequences & Solutions
Discover what happens when you miss a credit card payment, late fees, penalty APRs, and how to remove late marks.
 Tax & Retirement
Retirees: Making Tax Season Simple & Stress-Free
Navigate tax season with confidence. Discover essential tax tips, deductions, credits, and strategies.
 Debt Relief
Avoid Debt Negotiation Mistakes: 7 Costly Pitfalls
Learn the 7 critical debt negotiation mistakes that cost consumers thousands.
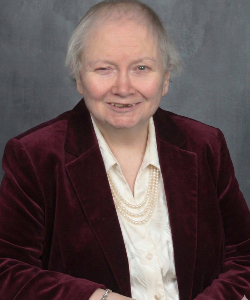
Loretta Kilday
Debt Relief Specialist & Spokesperson, DebtCC
Loretta Kilday, Esq., is an accomplished litigator and transactional attorney with more than 30 years of experience across debt collection, bankruptcy, and related matters. DebtConsolidationCare features her as its spokesperson and public voice. She earned her J.D. from DePaul University College of Law and a B.S. in Finance from DePaul University.