Understand your debt.Find your next step.
Explore clear explanations, free tools, and community support to help you compare debt options and make informed decisions.
 BBB Accredited Business since 2008
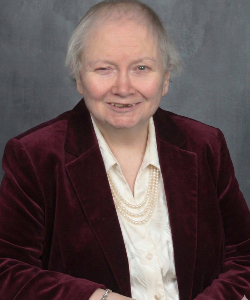 Legal counsel: Loretta Kilday, Esq.
- Sample letters and calculators, free to use
Request a free consultation
Step 1 of 2
About how much unsecured debt do you have?
Credit cards, medical bills, personal loans. Not your mortgage or car loan.
Step 1 of 2 · Free, no obligation
BBB Accredited Business since May 14, 2008View our BBB profileAs featured in
Start here
What do you need help with?
Compare your options
Four common ways out of debt, and what each one costs you
None of these is right for everyone. Each one trades something away.
Consolidation loan
A new loan pays off several debts. You repay one lender.
- You repay
- The full balance, over 2–7 years
- Credit impact
- Low
- Trade-off
- Needs fair-to-good credit. Easy to run cards up again.
Best for: Fair-to-good credit and a payment you can already keep up with.
Learn about consolidationDebt management plan
A nonprofit credit counselor arranges lower rates. You make one payment through them.
- You repay
- The full balance, over 3–5 years
- Credit impact
- Moderate
- Trade-off
- Monthly fee. Enrolled cards are usually closed.
Best for: Steady income and a plan to repay in full at lower interest rates.
Learn about DMPsDebt settlement
A company negotiates to pay creditors less than you owe, usually in lump sums.
- You repay
- Less than you owe, over 2–4 years
- Credit impact
- High
- Trade-off
- Fees, possible lawsuits, and forgiven debt may be taxable.
Best for: Falling behind on minimums, with money you can set aside each month.
Learn about settlementBankruptcy
A court discharges debts (Chapter 7) or sets a repayment plan (Chapter 13).
- You repay
- Some or none, depending on chapter
- Credit impact
- Highest, 7–10 years
- Trade-off
- Court and attorney costs. Public record.
Best for: Debt far beyond what you could repay, after other options are ruled out.
Learn about bankruptcyGeneral information, not legal or financial advice. Terms vary by state, lender, and provider. Read the full comparison
Our legal counsel
An attorney who works on debt and bankruptcy law
Loretta Kilday, Esq.DebtCC spokesperson and legal counsel
Loretta works on bankruptcy and debt collection law, and answers questions from DebtCC readers on those topics.
Free tools
Use these now. No account needed.
Sample letters for collectors and creditors
Ready-to-edit letters with plain-English instructions for when to send each one.
- Debt validationAsk a collector to prove the debt
- Cease and desistStop collection calls
- Goodwill removalAsk to remove a late payment
Community
Ask people who've dealt with the same debt
DebtCC forums
Post your question about a collector, a creditor or a repayment plan. Members and moderators reply with what worked for them.
Browse recent discussionsMember experiences
Read how other members handled collectors, settlements and repayment plans.
Read member experiencesQuestions
Before you decide
Straight answers about who we are, what's free, and what happens to your information.
Something else? Ask the community
Is DebtCC legitimate and accredited?
Is DebtCC a debt relief company?
What does it cost?
Will requesting a consultation affect my credit score?
What happens to my information?
Which debt option is right for me?
Free consultation
What happens after you send the form
You don't need a consultation to use anything on this site.
- 1You tell us your debt range and how to reach youTwo short steps. Nothing else is required.
- 2Your request goes to a debt relief providerA debt relief company that advertises on DebtCC receives your details.
- 3The provider contacts youThey ask about your debts and income, then explain what they offer.
- 4You decideNo fee to talk and no obligation to sign up.
 Start with step 1
- Debt relief can hurt your credit and may cost more than you expect once fees are added.
- Some creditors won't negotiate. Forgiven debt may be taxable.