
Debt Forgiveness: Forgiven But Not Forgotten
The concept of "debt forgiveness" sounds like an instant erase button—a complete undo of past financial struggles. However, while creditors or courts may discharge or forgive a balance, the financial paper trail rarely disappears overnight.
Understanding how forgiveness works, what credit reporting marks remain, and how the IRS treats forgiven balances ensures you navigate debt relief with total clarity.
How Debts Are Forgiven
Lenders do not write off debts out of benevolence. Debt forgiveness occurs primarily under three specific circumstances:
- Lump-Sum Settlement: Negotiating to pay a portion of the balance (e.g. 50%) while the creditor forgives the remaining amount.
- Hardship & Cancellation Programs: Government or institutional forgiveness rules for federal student loans or disaster relief.
- Bankruptcy Discharge: Court orders legally barring creditors from collecting eligible unsecured debts.
IRS Tax Impact (Form 1099-C)
When a creditor forgives $600 or more of debt, the IRS considers that canceled debt as taxable income. You may receive Form 1099-C unless you qualify for an IRS insolvency exception (Form 982).
How Payday Loans & Credit Cards Are Settled
Credit card issuers and payday loan companies frequently negotiate settlements on severely delinquent accounts because their alternative is total loss in bankruptcy.
Settlement Agreements
Account status changes to "Paid in Full for Less Than Agreed Amount," stopping collection calls while resolving the debt.
Internal Blacklisting
While the debt is legally resolved, the specific credit card lender may maintain internal records preventing you from opening new accounts with them for years.
How Student Loans Are Forgiven
Federal student loans offer structured forgiveness pathways—such as Public Service Loan Forgiveness (PSLF), Income-Driven Repayment (IDR) 20-to-25-year completion forgiveness, or Teacher Loan Forgiveness.
In contrast, private student loans rarely offer statutory forgiveness and must be resolved through hardship modification, refinancing, or settlement negotiations.
Bankruptcy's Impact on Debt Forgiveness
Bankruptcy grants a legal order discharging liability on eligible debts:
- Chapter 7 Bankruptcy: Liquidates non-exempt assets (if any) to discharge eligible credit card, medical, and personal debts within 3 to 4 months.
- Chapter 13 Bankruptcy: Reorganizes debts into a 3-to-5-year court-supervised repayment plan, discharging remaining eligible balances upon completion.
Are Debts Forgotten in Credit Records?
A common misconception is confusing the statute of limitations (the legal timeframe creditors have to sue you for debt) with the credit reporting period under the Fair Credit Reporting Act (FCRA).
- Late Payments & Charge-offs: Remain on credit bureau reports for 7 years from the date of initial delinquency.
- Chapter 7 Bankruptcy: Remains on credit reports as a public record for 10 years.
- Chapter 13 Bankruptcy: Remains on credit reports for 7 years from filing.
Rebuilding Financial Mindset After Forgiveness
True financial freedom isn't just about getting a debt forgiven—it's about transforming the habits that created the debt.
Rebuild by establishing an emergency fund equal to 3 to 6 months of living expenses, building positive payment history with secured credit cards, and adhering to strict monthly cash-flow budgets.
Conclusion & Strategic Summary
While debt forgiveness resolves legal liability, credit reporting entries and tax considerations remain active for years. Pair debt relief with disciplined habits to ensure past debt mess remains permanently in the past.
Recent & Important Articles
 Debt Settlement
How Much of a Debt Can You Hope to Erase in Debt Settlement?
Learn what determines how much debt may be reduced in settlement, including debt type, creditor behavior, and negotiation strategy.
 Debt Settlement
What Should You Include in Your Debt Settlement Letter?
Build a stronger settlement request using key financial hardship details and clear payment proposals.
 Tax & Retirement
Retirees: Making Tax Season Simple & Stress-Free
Navigate tax season with confidence. Discover essential tax tips, deductions, credits, and strategies for retirees.
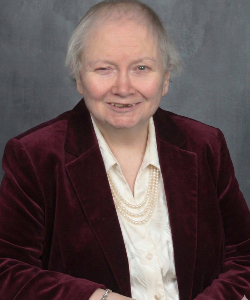
Loretta Kilday, Esq.
Debt Relief Specialist & Spokesperson, DebtCC
Loretta Kilday, Esq., is an accomplished litigator and transactional attorney with more than 30 years of experience across consumer finance, debt collection, and credit management. DebtConsolidationCare features her as its spokesperson and public voice.