
The year 2020 is coming towards us with lots of surprises, both good and bad. We should prepare ourselves for anything good, and also if anything bad happens. But one thing we can do is to make new year resolutions that can lead our life towards happiness in the coming year.
You need to decide your resolutions based on your prime life goals, mostly on your financial goals. Trust me, managing your debts or getting out of debt is the top priority financial goal in anyone's life. So, you must include debt resolutions as a part of your new year's financial resolution.
If you want to fit debt resolution into your financial resolution, the first thing you need to know is what is debt resolution and its aspects.
What Is Debt Resolution?
Many people believe that debt resolution and debt settlement are identical. The thing is true but there is a little difference between debt resolution and debt settlement. The objectives of both processes are the same - it is to lower your debt amount into a figure that is affordable to pay off easily.
Then what's the difference? Debt resolution will need the services of an attorney but debt settlement does not. To ease up the negotiation, debt settlement companies may require that the debtor should miss 2-3 payments. Debt resolution does not require missed payments.
Debt resolution attorneys
Work with you to negotiate with creditors and fix a repayment program.
Payments
Can be lump sum or spread over time based on negotiation.
Effect on credit scores
Will impact your score but potentially less than debt settlement.
Debt Resolution Attorneys
The debt resolution company attorney will help you to fix a debt repayment program according to your financial situation. The attorney would negotiate with each creditor so that they can accept a lower payment towards your debt.
It is up to the attorney how skillfully he/she manages to eliminate interest charges and other fees charged by the creditors. You don't have to miss any payment to get the debt resolution process started. This will make the creditors less aggressive towards you. As a result, you can expect that they won't take any direct legal action against you. If any legal matters arise in between, the attorney will handle them on behalf of you.
Payments
Debt resolution payments might be in a lump sum or spread over a while, based on how skillfully your debt attorney has managed your creditors and negotiated the terms.
The payment structure for debt resolution varies based on your attorney's negotiation with creditors. Payments can be arranged as a lump sum or distributed over time according to what best suits your financial situation.
Effect on Your Credit Scores
Debt resolution shares similarities with debt settlement - in both cases, you pay creditors less than the full amount owed. However, debt resolution may have a slight advantage since you don't have to stop making payments initially.
Late payments can affect your credit score and remain on your report for 7 years and 180 days. If your attorney can negotiate for the payment to be reported as "paid" rather than "settled," the impact on your score may be reduced. Your score will still be affected since you're paying less than the total debt owed.
Make continuous payments to creditors without missing any. Once you decide to pursue debt resolution, have your attorney begin negotiations immediately to settle the debt for a reduced amount while maintaining your payment history.
Financial Resolution #1: Saving Money
Building savings is one of the top financial priorities, with nearly half of Americans focusing on this goal. Key savings strategies include setting up automatic retirement contributions, taking advantage of High-Deductible Health Plans (HSA), and accumulating an emergency fund equal to 3 to 6 months of major expenses.
Financial Resolution #2: Paying Down High-Interest Debt
Eliminating high-interest debt is a critical financial priority. Create a chronological list of all debts, use proven repayment strategies like the snowball or avalanche methods, maintain minimum payments, and consider debt resolution or settlement to streamline your journey to becoming debt-free.
Financial Resolution #3: Control Spending
Controlling finances starts with smart budgeting strategies like the envelope method. Determine spending amounts for categories like groceries, entertainment, and transportation, allocate cash to dedicated envelopes, and spend strictly within those limits. Additionally, use cash over cards, limit credit card usage, and pay card balances in full each month.
Recent & Important Articles
 Debt Solutions
Complete Guide to Debt Settlement
Learn how debt settlement works and if it's the right solution for your situation.
 Debt Management
Debt Consolidation Explained
Discover how to simplify multiple debts into one manageable payment.
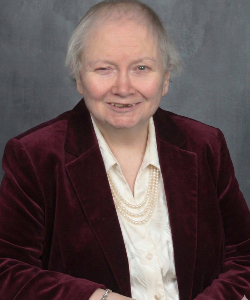
Loretta Kilday
Debt Relief Specialist & Spokesperson, DebtCC
Loretta Kilday, Esq., is an accomplished litigator and transactional attorney with more than 30 years of experience across debt collection, bankruptcy, and credit matters. DebtConsolidationCare features her as its spokesperson and public voice.