
In financial planning, what you avoid can be just as important as what you do.
These nine common don'ts can quietly weaken your budget, savings, credit profile, and retirement readiness. Use this checklist to prevent costly mistakes and build a stronger financial foundation.
1. Not making any financial plan
Not having a financial plan is one of the biggest personal finance mistakes. A budget gives direction to your money and helps you control expenses.
Start planning as early as possible—even during student life—so you can manage loans, spending, and future goals more effectively.
2. Do not mishandle your hard-earned money
Treat money with respect. Recover what you lend where appropriate, invest wisely, and leverage the power of compounding over time.
Careful handling of each dollar creates long-term financial stability.
3. Do not confuse between needs and wants
Many spending issues happen when wants are treated as needs. What feels urgent today may be completely optional tomorrow.
Clarifying this difference helps you prioritize essentials and avoid impulse buying.
4. Do not attach emotion to investments
Volatile markets can trigger fear-based decisions. Selling too quickly during short-term market dips can permanently damage long-term returns.
Stay informed and disciplined instead of reacting emotionally to temporary market swings.
5. Do not ignore your credit score
Your credit score influences loan approvals, interest rates, and overall borrowing costs. Neglecting it can make major financial goals much more expensive.
Monitor your credit reports regularly and correct errors early.
6. Do not get into debt problems
Unmanaged debt pulls your financial plan backward. Avoid borrowing for non-essential luxury purchases when your budget cannot comfortably support it.
Pay balances responsibly and seek professional credit counseling support if debt starts becoming difficult to manage.
7. Do not make only minimum monthly payments
Paying only minimums extends credit card debt repayment for decades and dramatically increases total interest charges.
A practical method is to keep minimum payments on all accounts while aggressively paying down one balance at a time.
8. Do not step into retirement with debt
Debt is far harder to manage after retirement when living on a fixed income.
Prioritize debt reduction before your retirement years to protect financial peace and independence later in life.
9. Stop procrastinating and make the first move
Delaying financial planning reduces the time available to fix mistakes and build compounding interest momentum.
Begin now, refine as you learn, and adjust with experience. Early action gives you flexibility and better long-term outcomes.
Ready to Build a Better Financial Plan?
Get expert guidance on debt management, budgeting, and repayment strategies tailored to your current financial situation.
Recent & Important Articles
 Personal Finance
Best Money Moves to Control Your Finances
Expert strategies to protect and manage your finances during economic uncertainty.
 Tax & Retirement
Retirees: Making Tax Season Simple & Stress-Free
Navigate tax season with confidence. Discover essential tax tips, deductions, credits, and strategies.
 Debt Relief
Avoid Debt Negotiation Mistakes: 7 Costly Pitfalls
Learn the 7 critical debt negotiation mistakes that cost consumers thousands.
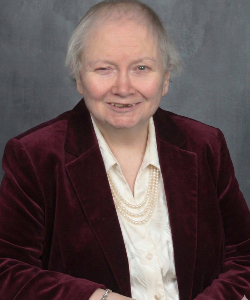
Loretta Kilday
Debt Relief Specialist & Spokesperson, DebtCC
Loretta Kilday, Esq., is an accomplished litigator and transactional attorney with more than 30 years of experience across debt collection, bankruptcy, and related matters. DebtConsolidationCare features her as its spokesperson and public voice. She earned her J.D. from DePaul University College of Law and a B.S. in Finance from DePaul University.