
Debt is indeed inevitable. Most of us can't buy a property or purchase a vehicle without taking out a loan. Moreover, debt helps us build our credit score. But, the question is "How much debt is too much?"
Will it be possible for you to reply to it with a number? Probably not. Debt is too much when you can't manage it properly.
Do you think that you have good financial habits and make the right decisions that will help you stay away from debt forever? Even if you plan a budget and try to live within your means, you may have certain habits and may make certain decisions that can lead you to face debt problems. Check out whether or not you have these habits, which may compel you to worry about debt in the future.
14 Habits and Decisions Which May Lead to Debt Problems
Even with good intentions, certain habits and financial decisions can lead you toward debt problems. Here are 14 common behaviors to watch out for:
1. Oh, credit cards, the devil you!
Many consumers don't understand how credit cards work. When they don't have enough money to buy something, they unknowingly use credit cards. After a few days when they receive credit card bills, they fail to pay the full amount. Instead, they pay the minimum amount. And, this creates the habit of not paying credit card bills in full monthly. Thereafter, the high interest rate and late payment fees eat up their future income gradually.
2. Using plastic money to buy every item
Most of us carry at least 1 credit card in a wallet. According to Experian, the average American has 3.06 credit cards. If you have multiple credit cards, then you may have an increased tendency to spend. The existence of credit cards may lead you to develop an over-consumption pattern, which isn't healthy for your financial life.
3. Not having a proper budget
67% of people say they have a budget, which also means that 33% of people don't have a budget. If you are one of them, then you need to be very concerned. Legendary investor Warren Buffett says, "Someone is sitting in the shade today because someone planted the tree a long time ago." It means, to enjoy the shade, you need to plan first.
4. Being more extravagant than what you can afford
If you keep on spending beyond your means, then you'll definitely fall into debt. Allocate an amount for every item in your budget. If possible, reduce the allotted amount a little bit more. However, remember you don't have to go to the extreme to find that perfect balance.
5. Living paycheck to paycheck
Based on a report, living costs have increased by 26.5%, whereas income has risen by only 7% over the last 8+ years. Living paycheck to paycheck means if you fall victim to a job loss or sudden emergency, you may not be able to pay off your bills on time.
6. Not understanding what is a need and what is a want
Many consumers fail to differentiate between need and want. A need is essential for survival—utility bills, food, housing. A want is a luxury—expensive branded bags, unnecessary traveling, designer shoes. Wants often push consumers into heavy debt.
7. Taking out loans to pay off existing debt
According to Experian, 26% of consumers resort to debt consolidation and 9% refinance their home to pay off existing debts. Taking out a loan to pay off existing debt is a good idea only if you know the terms properly; otherwise, you may fall into a deeper debt trap.
8. Opting for payday loans for day-to-day expenses
70% of borrowers use payday loans to cover utility bills, rent, and basic expenses. Interest rates for payday loans often exceed 300% APR. Being trapped in a payday loan cycle leads to escalating debt.
9. Not saving for emergencies
Without adequate emergency savings, any unexpected medical bill, car repair, or job loss forces you to rely on credit cards, rapidly accumulating high-interest debt.
10. Choosing costly colleges without a career plan
Students often take out massive student loans without a clear career roadmap. Before taking on heavy student debt, ensure you have a realistic career plan and earning potential evaluation.
11. Buying items solely because of low initial interest rates
Purchasing non-essential items just because they offer low promotional APRs is a trap. Instead of financing impulse purchases, save that money in an emergency or retirement fund.
12. Telling financial lies to your loved ones
37% of adults admit to lying about purchases or accounts, while 18% lie about debts. Financial infidelity damages trust and delays seeking necessary financial help.
13. Not planning for retirement
Relying on luck or delaying retirement contributions leaves you vulnerable later in life. Without adequate savings, fixed expenses will quickly turn into unmanageable debt in retirement.
14. Hiding financial hardship from creditors
Ignoring creditors when money gets tight leads to default and legal action. Communicating early allows creditors to offer hardship programs or temporary payment relief.
14 Alarming Signs You're Heading Into Knee-Deep Debt
If you notice multiple signs from this list, it's time to take immediate action before your debt becomes unmanageable:
1. You've been denied credit by a lender
When a lender denies your application, it indicates your Debt-to-Income (DTI) ratio is too high or your credit risk is elevated—a major red flag.
2. You're consistently late with monthly payments
Consistently missing payment due dates damages your credit score and adds expensive late fees to mounting balances.
3. You can't afford basic bill payments
When cash flow falls short of covering routine monthly bills, penalties accumulate and debt compounding accelerates.
4. You have ZERO emergency savings
Living without a savings cushion leaves you one unexpected expense away from severe financial distress.
5. Debt constant anxiety dominates your thoughts
When debt worries consume daily mental energy, the financial burden has exceeded healthy limits.
6. You require extreme measures just to meet minimums
Needing emergency cutbacks simply to cover minimum payments signals that your baseline debt load is unsustainable.
7. You don't know your exact total debt balance
Avoiding account statements out of fear hides the true scope of your financial obligations.
8. You lack a structured debt payoff plan
Without a clear repayment strategy, interest charges continue to eat up payments while principal balances remain unchanged.
9. You use one credit card to pay another
Juggling balances between credit cards or taking cash advances to meet minimums creates an escalating debt spiral.
10. You frequently borrow money from friends or family
Relying on personal loans for routine costs strains relationships and indicates fundamental budget deficits.
11. Your accounts are sent to debt collection
According to the Urban Institute, nearly 1 in 3 adults have debt in collections. This severely damages your credit score and opens risk of wage garnishment.
12. Credit issues affect job opportunities
Employers in finance and security sectors run credit checks. Severe debt can block employment opportunities.
13. Financial stress harms your personal health
Persistent financial pressure causes insomnia, strain in marriages, and chronic physical stress.
14. You suffer from anxiety or panic over collection calls
When debt calls trigger severe panic, professional financial debt counseling is urgently required.
How Can You Figure Out How Much Debt Is Too Much?
Determining whether your debt is manageable depends on key financial benchmarks across your income and loan types:
Auto Loan Guidelines
Auto payments should be 5–10% of gross monthly income. Aim for a 20% down payment and 4-year max loan term.
Student Loan Guidelines
Keep monthly student debt payments below 10% of gross monthly income based on your post-graduation salary.
Mortgage Guidelines
Housing payments should not exceed 25% of gross income to leave adequate buffer for living costs and emergency savings.
Credit Card Rule
Never revolve credit card balances. Pay statements in full each month to prevent compound interest accumulation.
Calculate Your Debt-to-Income (DTI) Ratio
Divide your total monthly debt payments by your gross monthly income. A DTI ratio is considered healthy when kept under 36% (and ideally below 25% for non-mortgage consumer debt).
Self-Analysis Check: Are You Over-Indebted?
- Are you relying on credit cards for basic daily groceries and utilities?
- Are you making only minimum payments across all active credit card accounts?
- Have your credit lines reached maximum limits?
- Are financial anxieties impacting your work performance or personal relationships?
How Can You Overcome Debt If It's Too Much for You?
If your debt burden has become overwhelming, take practical and structured steps immediately to regain control:
1. Follow the 50/30/20 Budgeting Rule
Allocate 50% of income to essential living expenses, 20% directly toward debt payoff and savings, and limit discretionary spending to 30%.
2. Pause New Credit Card Usage
Switch exclusively to cash or debit cards while paying down debt to avoid adding new charges to existing balances.
3. Implement Debt Snowball or Avalanche Strategy
Choose the Snowball method (paying smallest balances first for momentum) or the Avalanche method (paying highest interest accounts first to minimize cost).
4. Sell Unused Household Assets
Liquidate spare electronics, furniture, or unused belongings to generate lump-sum payments toward high-interest debts.
Professional Debt Relief Options
Debt Consolidation
Combines multiple high-interest debts into a single structured monthly payment with a lower fixed interest rate.
Debt Settlement
Negotiates with creditors to settle principal balances for less than the original amount owed.
Bankruptcy (Chapter 7 / 13)
A legal relief measure used as a last resort when obligations exceed all repayment capacity.
Conclusion & Final Words
Recognizing the early warning signs of debt allows you to take decisive action before your finances spiral out of control. By modifying spending habits, creating a disciplined payoff plan, or leveraging debt relief programs, you can achieve lasting financial independence.
The Bottom Line
Debt doesn't have to define your financial future. Early recognition, strict budgeting, and seeking expert counsel when needed are key to breaking free from the debt trap.
Drowning in Debt? We Can Help
If you're experiencing warning signs of unmanageable debt, our certified counselors can assist you with custom debt management and consolidation strategies.
Get Free Financial CounselRecent & Important Articles
 Money Management
How to Stop Spending More Than What You Earn
Practical strategies to control spending and live within your means.
 Credit Journal
Tips to Improve Credit Score Components
A detailed breakdown of five core credit score factors and practical strategies to optimize your score.
 Tax & Retirement
Retirees: Making Tax Season Simple & Stress-Free
Navigate tax season with confidence. Discover essential tax tips, deductions, credits, and strategies for retirees.
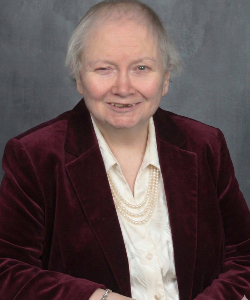
Loretta Kilday
Debt Relief Specialist & Spokesperson, DebtCC
Loretta Kilday, Esq., is an accomplished litigator and transactional attorney with more than 30 years of experience across debt collection, bankruptcy, and related matters. DebtConsolidationCare features her as its spokesperson and public voice. She earned her J.D. from DePaul University College of Law and a B.S. in Finance from DePaul University.