
Introduction
Are you looking for a suitable mortgage loan? Even if you are not looking for a home loan right now, understanding how taking out a mortgage impacts your credit score ensures you are well-prepared for homeownership.
A mortgage is typically the largest financial commitment an individual takes on. While it adds substantial debt to your profile, a home loan can also serve as a powerful tool for building high long-term credit scores.
1. How a Home Loan Affects Your Debt-to-Income Ratio
Your debt-to-income (DTI) ratio compares how much you earn each month against how much you owe in recurring debt payments to creditors.
Mortgage lenders prefer a overall DTI ratio below 36% (with no more than 28% allocated to housing costs). A DTI ratio approaching or exceeding 50% signals financial distress and makes obtaining competitive mortgage approval difficult.
When buying a home, remember to factor maintenance costs, property taxes, homeowner insurance, and HOA fees into your budget alongside principal and interest payments.
Key Advice: Pay down credit cards and personal loans prior to submitting mortgage applications to keep your DTI low and qualify for lower interest rates.
2. How a Mortgage Loan Helps in Achieving High Score
Yes, taking out a mortgage loan can significantly elevate your FICO credit score over time—provided you consistently make all monthly payments on time.
Adding an installment mortgage loan diversifies your credit mix (combining revolving credit cards with fixed installment loans), which accounts for 10% of your credit score. Furthermore, a multi-year history of flawless mortgage payments builds an exceptional payment track record.
Pro Tip: Consider setting up biweekly mortgage payments to align with paychecks, reduce total lifetime interest, and ensure automated, on-time payments.
3. How a Home Loan Can Hurt Your Score
While on-time mortgage payments improve credit, late or missed payments cause substantial drops in credit ratings. Even a single 30-day late mortgage payment can lower a high credit score by 60 to 100 points.
Initial hard inquiries during the rate-shopping period will temporarily dip your credit score by a few points. Additionally, if you select an Adjustable-Rate Mortgage (ARM), interest rates may reset upward in future years, increasing your monthly obligation.
Mortgage Precautions:
- • Check credit reports from Experian, TransUnion, and Equifax before applying.
- • Consolidate rate-shopping inquiries within a 14-to-45-day window to minimize credit score impact.
- • Maintain a post-closing emergency fund equal to 3–6 months of mortgage payments.
Conclusion & Bottom Line
Taking out a home loan causes a brief initial credit dip from hard inquiries and new debt balance, but managing your mortgage responsibly builds outstanding long-term credit health and home equity.
Keep your DTI low, automate payments, and choose loan terms you can comfortably afford through all financial seasons.
Plan Your Home Loan Wisely
Need assistance optimizing your debt-to-income ratio or managing existing debts to qualify for better mortgage rates? Speak with a DebtCC debt specialist.
Get Free ConsultationRecent & Important Articles
 Credit Repair
Useful credit repair tips for single moms
Essential strategies for single mothers to improve their credit scores.
 Women & Finance
8 Common financial mistakes that women make
Avoid these pitfalls to achieve lasting financial stability.
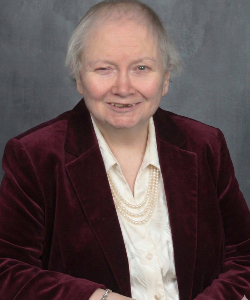
Loretta Kilday, Esq.
Debt Relief Specialist & Spokesperson, DebtCC
Loretta Kilday, Esq., is an accomplished litigator and transactional attorney with more than 30 years of experience across consumer finance, debt collection, and credit management. DebtConsolidationCare features her as its spokesperson and public voice.