
Introduction
Unlike previous generations who embraced credit cards in early adulthood, millennials (born 1981–1996) are notoriously cautious about opening revolving credit lines. Industry studies show that a significant percentage of millennials carry fewer credit cards—or avoid credit cards entirely—compared to Gen Xers and Baby Boomers at the same age.
While avoiding high-interest consumer debt is admirable, total credit avoidance creates unexpected financial hurdles when applying for mortgages, renting apartments, or financing vehicles.
Let's explore why millennials are credit card wary, the hidden costs of credit avoidance, and how to use credit cards safely without falling into debt traps.
1. Why Millennials Fear Credit Cards: Student Debt & Recession
Millennial credit hesitancy is rooted in major economic events that shaped their formative financial years:
Record Student Loan Balances
Millennials entered adulthood carrying unprecedented student loan debt. Adding 20%+ APR credit card balances to existing monthly loan payments felt financially overwhelming.
The Great Recession Financial Trauma
Witnessing parents lose homes, lay off jobs, and drown in credit card debt during the 2008 financial crisis instilled a deep fear of borrowing money.
CARD Act Regulations
The 2009 CARD Act restricted credit card companies from offering free gifts and easy approvals on college campuses, requiring under-21 applicants to have independent income or co-signers.
2. The Shift to Debit Cards & Buy-Now-Pay-Later (BNPL)
Seeking control over daily spending, millennials turned overwhelmingly to debit cards, prepaid cards, and fintech budgeting apps. Spending money directly from checking accounts provided an immediate sense of financial discipline.
Additionally, the rise of Buy Now, Pay Later (BNPL) services (such as Klarna, Affirm, and Afterpay) offered structured short-term installment loans for online shopping without traditional credit card APR compounding.
4. 5 Rules for Millennials to Use Credit Responsibly
You can build a top-tier 750+ credit score without ever paying a dime in interest. Follow these 5 proven rules:
- Treat Credit Cards Like Debit Cards: Never make a purchase on a credit card unless you already have the liquid cash in your checking account to pay for it immediately.
- Pay the Full Statement Balance Every Month: Carrying a balance does not help your credit score; it only generates high interest charges. Pay in full by the due date to enjoy a 0% effective rate.
- Keep Credit Utilization Under 10%–30%: Never max out your credit card limit. If your limit is $1,000, keep your reported balance under $300 (ideally under $100) before statement closing dates.
- Automate One Fixed Small Recurring Bill: Put a single recurring bill (like Netflix or mobile phone service) on auto-pay with your credit card, then set the credit card to auto-pay in full from your checking account.
- Start with a Secured Card or No-Fee Rewards Card: If you have no credit history, open a secured credit card backed by a refundable deposit or a basic cash-back card with zero annual fee.
Conclusion & Strategic Summary
Being credit card wary is a healthy protective instinct, but total credit avoidance can cost you thousands in missed rewards and higher borrowing rates down the road.
By treating your credit card like a debit card, paying balances in full, and automating monthly payments, you can leverage credit to build an stellar FICO score while remaining completely debt-free.
The Bottom Line
Don't fear credit cards—master them. Pay your full statement balance monthly, keep utilization below 30%, automate recurring payments, and enjoy credit score growth and fraud protection with zero interest fees.
Need Guidance on Credit Score Building & Debt Payoff?
Our credit specialists and financial counselors can help you design a customized plan to eliminate debt, boost your credit score, and build financial confidence.
Get Free Credit & Debt CounselRecent & Important Articles
Credit9 Rules for Credit Card Newbies to Build Healthy Spending
Obtaining your first credit card can be an exciting rite of passage. Learn these essential rules to build a healthy credit foundation.
 Work & Income
Best Side Hustle Ideas & Investment Strategies for Millennials
Discover top side hustles and smart investment strategies tailored specifically for millennials to build wealth.
 Personal Finance
Today's Kids Look at Money Differently: Gen Z & Millennial Habits
Explore how millennials and Gen Z redefine spending, tech investments, and debt awareness.
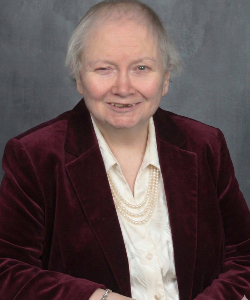
Loretta Kilday, Esq.
Debt Relief Specialist & Spokesperson, DebtCC
Loretta Kilday, Esq., is an accomplished litigator and transactional attorney with more than 30 years of experience across consumer finance, debt collection, and credit management. She helps young adults and millennials build healthy credit habits.