
Introduction
When it comes to money management, a standard personal finance strategy that people adopt is to pay all necessary expenses first—including bills, rent, and debt repayments—and then save whatever is leftover.
However, if your income is tight or variable, saving as an afterthought often results in saving nothing at all. The "Pay Yourself First" strategy flips this paradigm on its head, treating your personal savings as the very first bill you pay every month.
What is the 'Pay Yourself First' Strategy?
The "Pay Yourself First" strategy is a reverse-budgeting method where you set aside a predetermined portion of your income into savings or investments immediately upon getting paid, before paying for recurring living expenses or discretionary spending.
How Does It Work?
By setting up automatic transfers from your checking account to a dedicated savings or investment account on payday, saving becomes effortless. You then adapt your lifestyle and daily spending to fit the remaining balance.
Important Savings Goals to Consider
1. Emergency Fund
Build a safety cushion equal to 3 to 6 months of living expenses. Having separate funds for job loss, medical emergencies, or car repairs protects you from turning to high-interest credit cards when unexpected bills arise.
2. Retirement Contributions
Allocate funds directly to employer-matched 401(k) plans or individual Roth IRAs. Automatic payroll deductions ensure consistent long-term wealth building with compound growth.
3. Major Life Purchases & Down Payments
Whether saving for a house down payment, education expenses, or buying a replacement vehicle, breaking down large target sums into small, regular contributions makes major goals achievable.
4. Targeted Debt Repayment
Paying yourself first can also mean setting aside extra funds to accelerate debt payoff above minimum payments, freeing up future cash flow faster.
Steps to Save Money with this Strategy
- Calculate Net Monthly Income: Tally up all income sources after taxes to establish your baseline monthly cash flow.
- Define Clear Savings Targets: Determine how much you need for short-term and long-term goals, establishing realistic target amounts.
- Automate Account Transfers: Schedule automatic recurring transfers from your checking to high-yield savings accounts immediately following payday.
- Review and Adjust Periodically: Re-evaluate your budget every 3 to 6 months or whenever your income changes to increase your savings rate gradually.
Ways To Budget with the 'Pay Yourself First' Method
- Treat Savings as a Non-Negotiable Bill: Categorize your monthly savings transfer with the same urgency as rent or utility bills.
- Use Multiple Specialized Accounts: Keep checking for daily spending, high-yield savings for emergencies, and fixed-cost accounts for bills.
- Start Small and Build Momentum: If money is tight, start saving just 2% to 5% of your income. Once comfortable, raise the percentage incrementally.
- Leverage Budgeting Apps: Utilize tools like YNAB or PocketGuard to visualize spending and prevent accidental overspending.
Is the 'Pay Yourself First' Method a Good Choice?
Yes. Studies show that individuals who automate their savings build significantly larger emergency funds and wealth over time compared to those relying on manual savings habits.
By making savings automatic and non-negotiable, you guarantee consistent progress toward your financial independence regardless of market fluctuations or daily temptations.
Recent & Important Articles
 Money Management
Couples Guide to Successful Money Management
Practical strategies for couples to manage joint finances, create household budgets, and reach shared goals.
 Debt Relief
How to Manage Debt Effectively
Actionable steps to control debt, eliminate high-interest balances, and maintain financial peace of mind.
 Personal Finance
How Women are Better Money Managers and Tips of Managing Money
Discover key financial traits and proven strategies to cut expenses while continuing to enjoy life.
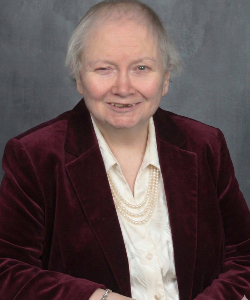
Loretta Kilday
Debt Relief Specialist & Spokesperson, DebtCC
Loretta Kilday, Esq., is an accomplished litigator and transactional attorney with more than 30 years of experience across debt collection, bankruptcy, and related matters. DebtConsolidationCare features her as its spokesperson and public voice. She earned her J.D. from DePaul University College of Law and a B.S. in Finance from DePaul University.