
A 401(k) plan is one of the best ways to save for retirement. It helps reduce taxable income while allowing your money to grow for the future.
But many employees still make mistakes before and after contributing. Some invest in the wrong places, while others misuse the fund altogether. Here are four things you should avoid while contributing to a 401(k).
1. Not looking for the percentage you're contributing
Many companies automatically enroll employees into 401(k) plans at a low contribution rate. That can leave workers saving far less than they expect.
Check your paycheck and confirm the exact percentage being contributed. A common target is around 10% to 15% of income for retirement savings, though your own plan may differ. Small contribution changes today can make a major difference over time.
2. Gambling your money on high-risk investments
High yields can look attractive, but high-risk investments can expose retirement money to large losses. That is especially dangerous when the money is meant to last for decades.
Examples of high-risk options:
- Leveraged oil ETFs
- Currency trading
- Venture capital
- Foreign emerging markets
- REITs
- High-yield bonds
- Stock market speculation
If you are new to investing, it is usually better to choose diversified mutual funds or similar balanced options rather than chasing risky returns.
3. Heavily borrow money from your 401(k)
Your 401(k) is meant to support future retirement, not short-term spending needs. Borrowing from it can weaken your long-term security.
Withdrawals before age 55 may create serious consequences, including taxable income and an additional early distribution penalty. Even a loan can interrupt growth while the money is out of the account. If possible, look for other solutions before touching retirement savings.
4. Not thinking about your asset allocation
Putting all your retirement money into one company, one stock type, or one aggressive option creates unnecessary concentration risk.
A proper asset mix should reflect your age, goals, and risk tolerance. Younger investors can often handle more growth-oriented exposure, while older investors usually need more balanced protection. Diversification is one of the simplest ways to protect a 401(k) from avoidable volatility.
Need Help Reviewing Your Debt or Retirement Strategy?
If you are balancing retirement savings with debt repayment, talk to a professional about the safest path forward to protect your financial future.
Recent & Important Articles
 Tax & Retirement
Retirees: Making Tax Season Simple & Stress-Free
Navigate tax season with confidence. Discover essential tax tips, deductions, credits, and strategies.
 Retirement
Proven Ways to Boost Retirement Savings
Discover 6 proven tips to grow your 401(k) and IRA retirement accounts faster.
 Saving
Are You a Good Saver? Money Mistakes to Avoid
Practical guidance to improve your saving habits and reduce wasteful spending.
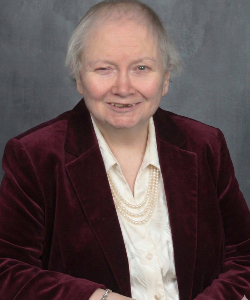
Loretta Kilday, Esq.
Debt Relief Specialist & Spokesperson, DebtCC
Loretta Kilday, Esq., is an accomplished litigator and transactional attorney with more than 30 years of experience across consumer finance, debt collection, and credit management. DebtConsolidationCare features her as its spokesperson and public voice.