
Introduction: How the Debt Industry Keeps Growing
Consumer debt has become an integral aspect of modern financial life for millions of households. In theory, debt serves as a useful economic tool to smooth cash flow, finance higher education, or purchase real estate. In practice, however, much of the consumer credit market thrives on persistent balances, high servicing costs, and financial vulnerability.
To understand what fuels the debt industry, we must look beyond individual borrowing decisions and examine systemic drivers: lender pricing structures, aggressive marketing, stagnant real wages, and behavioral loops that keep consumers trapped in high-interest cycles.
Easy Credit and Aggressive Lending
The debt market expands rapidly when credit is widely accessible and marketed as frictionless. Pre-approved credit card offers, instant digital approvals, and "buy now, pay later" financing lower the psychological barriers to incurring debt.
Many borrowers commit to monthly payments without fully calculating the long-term compounding cost of carrying debt over multiple years.
High-Interest Products and Fee Traps
Interest income and penalty fees form the core revenue engine of the debt industry. When annual percentage rates (APRs) are elevated and late fees accumulate, even disciplined borrowers struggle to reduce principal balances.
!Key Cost Drivers in High-Interest Debt
- Compounding Interest: High APRs ensure that the majority of minimum payments cover interest rather than principal reduction.
- Penalty Pricing: Default interest rates triggered by a single late payment can increase interest rates above 29%.
- Rollover and Refinancing Fees: Fee structures in short-term and subprime products turn temporary obligations into recurring financial burdens.
Low Financial Literacy
A lack of practical financial education leaves many consumers unaware of how credit utilization, minimum payment traps, and compounding interest impact long-term net worth.
Without these core fundamentals, borrowers undercount total payoff costs and overestimate affordability, sustaining demand for continuous debt refinancing.
Income Shocks and Weak Safety Nets
Unexpected events such as job displacement, medical emergencies, rental increases, or urgent home repairs force families to rely on credit cards to cover basic living expenses.
When household income fails to keep pace with living costs, credit becomes a surrogate for income, pushing consumers from short-term financial stress into persistent structural debt.
Behavioral Spending Loops
Financial anxiety, lifestyle inflation, and convenience-first spending create self-reinforcing debt cycles. Borrowers often use credit to alleviate short-term stress, only to face higher monthly obligations that elevate long-term anxiety.
What Actually Helps Consumers
Breaking free from systemic debt cycles requires a combination of structured personal finance strategies and clear consumer protections:
Effective Debt Elimination Moves
- Lower Servicing Costs: Use low-rate consolidation loans, balance transfers, or debt management plans to stop compounding interest.
- Establish Liquid Reserves: Build even a small emergency savings fund to prevent relying on credit cards during unexpected expenses.
- Adopt Clear Payoff Frameworks: Prioritize high-interest balances systematically using the debt avalanche or debt snowball method.
Final Takeaway & Summary
The debt industry thrives on the intersection of aggressive product design, economic pressure, and consumer financial gaps. By understanding these underlying mechanisms, consumers can regain financial control: choosing lower-cost repayment options, avoiding high-fee credit products, and building resilient cash reserves.
Recent & Important Articles
 Debt Psychology
Psychology of Debt: Why It Feels So Heavy
Understand the emotional and behavioral side of debt and how it affects financial decision-making.
 Financial Planning
Best Money Moves to Control Your Finances
Practical money actions that improve cash flow and reduce long-term consumer debt risk.
 Tax & Debt
Are Debt Consolidation Fees Tax Deductible?
Find out whether debt consolidation fees are tax deductible and when tax benefits apply.
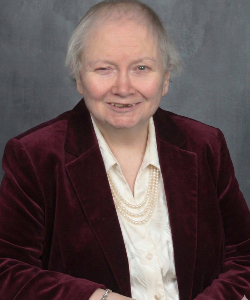
Loretta Kilday
Debt Relief Specialist & Spokesperson, DebtCC
Loretta Kilday, Esq., is an accomplished litigator and transactional attorney with more than 30 years of experience across debt collection, bankruptcy, and related matters. DebtConsolidationCare features her as its spokesperson and public voice. She earned her J.D. from DePaul University College of Law and a B.S. in Finance from DePaul University.