
Debt, Behavior, & Mental Health Connections
Debt is rarely just a mathematical equation of income minus expenses. For many individuals, escalating balances trigger chronic anxiety, insomnia, depression, and severe emotional trauma.
When financial stress begins to affect your mental health, a crucial question arises: Should you seek financial counseling, psychological therapy, or a combination of both?
The key to breaking the cycle of financial trauma lies in understanding how habits, emotional triggers, and credit management interact.
1. Household Debts as a Product of Habits
High credit card balances and personal loan debt often stem from subtle, repetitive behavioral habits rather than sudden financial emergencies.
Impulse buying, retail therapy, and using credit cards to cope with stress or mood fluctuations create a cycle where emotional relief is temporarily achieved at the expense of future financial stability.
Recognizing Habit-Driven Debt Signals:
- •Shopping online when feeling stressed, anxious, or lonely.
- •Hiding store receipts or financial statements from family members.
- •Experiencing post-purchase guilt or remorse after non-essential shopping.
2. Overspending & The Credit Trap Cycle
When credit card limits are treated as available spending power rather than borrowed money, the tendency to overspend increases. This cognitive shift distorts budget awareness.
As total debt balances grow, monthly minimum payments rise, creating constant financial pressure. To relieve this stress, individuals may resort to emotional spending again, creating a self-reinforcing trap.
3. Addressing Emotional & Psychological Triggers
If your debt stems from underlying emotional habits, attempting to fix the issue purely through spreadsheets or strict budgets often fails.
Addressing the Root Cause First
Working with a mental health therapist or licensed counselor helps identify underlying emotional triggers (such as depression, anxiety, or compulsive habits). Once emotional coping mechanisms are healthy, debt reduction strategies can stick long-term.
4. Should You Seek Money Help or Mind Help?
In most cases of financial trauma, the most effective solution is a dual-track approach:
Money Help (Financial Counseling)
Accredited credit counselors help structure debt management plans, negotiate interest rates, and build realistic monthly budgets.
Mind Help (Psychological Support)
Therapists provide cognitive behavioral tools to process financial anxiety, curb compulsive shopping, and restore emotional stability.
Summary & Recovery Roadmap
Overcoming debt trauma requires treating both the financial numbers and emotional well-being. By pairing professional credit advice with mental health support, you build a sustainable foundation for long-term financial freedom and mental peace.
Recent & Important Articles
 Debt Psychology
Psychology of Debt: Why We Overspend
Understand the emotional patterns and cognitive biases that keep debt cycles active.
 Financial Wellness
How to Curb Financial Anxieties
Practical steps to reduce money stress, eliminate panic, and build healthier financial habits.
 Savings
Why Emergency Funds Are Crucial for Financial Resilience
Learn how to build, maintain, and structure a high-yield liquid emergency fund for peace of mind.
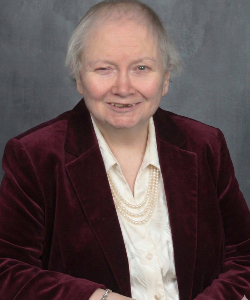
Loretta Kilday, Esq.
Debt Relief Specialist & Spokesperson, DebtCC
Loretta Kilday, Esq., is an accomplished litigator and transactional attorney with more than 30 years of experience across consumer finance, debt collection, and credit management. DebtConsolidationCare features her as its spokesperson and public voice.