
Who Controls Your Financial Life?
Debt can feel overwhelming, but financial control still starts with personal choices. The core question is whether spending habits lead your life, or whether you choose disciplined money behavior and long-term stability.
Reversing debt pressure begins with honest awareness and consistent boundaries.
What Makes People Fall Into Debt?
A common root is desire-driven spending beyond available income. Psychological triggers such as instant gratification and deferred payment convenience make borrowing feel easier than it is.
The Cycle of Unchecked Spending
Over time, this pattern normalizes debt until monthly obligations outgrow financial capacity, forcing individuals to spend more income paying off past purchases instead of funding current life goals.
Credit Card Overuse Trap
Multiple cards for nonessential spending often create fragmented balances and high interest burden. Minimum payments hide the true repayment timeline and keep debt alive.
Using credit mainly for genuine emergencies can reduce this risk significantly.
Payday Loan Debt Spiral
Payday loans can carry extremely high costs and frequently trap borrowers in rollover cycles. What begins as short-term cash relief can quickly become recurring debt pressure.
High-Risk Trap
Avoiding this category of high-interest predatory borrowing is often one of the fastest ways to prevent severe debt acceleration.
Needs Versus Wants
Financial control depends on distinguishing essential expenses from optional lifestyle spending. Debt often grows when wants are repeatedly financed as if they were needs.
A strict prioritization rule helps redirect cash flow toward debt reduction.
Budgeting to Stop Debt Growth
A practical budget framework, such as a structured percentage allocation model, creates discipline for essentials, savings, and discretionary spending.
Applying this structure consistently can stabilize monthly cash flow and reduce reliance on new debt.
How Not to Let Debt Control Life
Debt consolidation can simplify payments, settlement may reduce total dues, and bankruptcy can provide legal relief when debt is truly unmanageable. Each path serves different debt profiles.
Exploring Core Debt Relief Options:
- Debt Management / Consolidation: Combine multiple accounts into one lower monthly payment.
- Debt Settlement: Negotiate with creditors to resolve balances for less than owed.
- Bankruptcy Protection: Legal court process (Chapter 7 or 13) to discharge overwhelming debts.
Choosing the right option early often prevents deeper financial and emotional stress.
Final Thoughts
Debt should never be the decision-maker in your life. With stronger habits, clear budget rules, and the right relief tools, you can regain control and protect your future financial freedom.
Real change starts when spending becomes intentional and debt decisions become strategic.
The Bottom Line
You are in control of your financial destiny, not your debt. By establishing boundaries, trimming unnecessary costs, and seeking professional advice when necessary, you can achieve long-term financial independence.
Struggling to Break Free From Overwhelming Debt?
Our certified debt counselors can analyze your debts, explain consolidation, settlement, and bankruptcy options, and help you regain financial control.
Get Free Debt AdviceRecent & Important Articles
 Budgeting
Realistic Budget Tips
Build a practical spending plan that helps you control debt before it compounds.
 Debt Relief
Get Out of Debt While Being Unemployed
Explore actionable debt strategies when income is limited and stress is high.
 Tax & Retirement
Retirees: Making Tax Season Simple & Stress-Free
Navigate tax season with confidence. Discover essential tax tips, deductions, credits, and strategies for retirees.
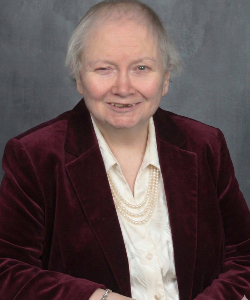
Loretta Kilday
Debt Relief Specialist & Spokesperson, DebtCC
Loretta Kilday, Esq., is an accomplished litigator and transactional attorney with more than 30 years of experience across debt collection, bankruptcy, and related matters. DebtConsolidationCare features her as its spokesperson and public voice. She earned her J.D. from DePaul University College of Law and a B.S. in Finance from DePaul University.