How to Recognize and Avoid Credit Repair Scams in Nevada
Learn how to spot credit repair scams, know your rights under federal law, avoid illegal tricks, and fix your credit for free.
Written by Loretta Kilday, Attorney and Spokesperson, Debt Relief Specialist & Spokesperson
• Reviewed by the DebtCC Editorial Team
KEY TAKEAWAYS
- Under the Credit Repair Organizations Act (CROA), it is illegal for credit repair companies to demand payment before services are completed.
- No company can legally erase accurate negative records, as explained in detail below.
- Never use a CPN (Credit Privacy Number) on credit applications. Using a CPN in place of your SSN can expose you to federal fraud charges.
- You have the legal right under FCRA to dispute inaccurate items directly with Equifax, Experian, and TransUnion completely free of charge.
Quick Answer:
Federal law bans these companies from charging you before they finish work. No company can legally remove accurate, verified information. You can dispute real errors yourself for free through Equifax, Experian, and TransUnion.
If your credit score is low and you're trying to buy a home or get approved for a car loan, it can feel like nothing is moving fast enough. That feeling is exactly what scammers count on.
These scammers promise to increase your credit score quickly or guarantee they can remove a bankruptcy from your record. They charge steep fees for work that is useless or against the law. You don't need a lawyer to protect yourself, just a clear sense of what real credit repair looks like versus a scam.
What Is a Credit Repair Scam?
A credit repair scam happens when a company takes upfront payment to fix your credit score. It makes false claims about what it can legally do. They often claim they use secret legal methods or have personal contacts at the credit bureaus to delete your bad debt records.
Credit bureaus, by law, must report accurate history, like late payments, tax liens, repossessions and foreclosures.
What Is the Difference Between Legitimate Credit Repair and a Scam?
The Federal Trade Commission (FTC) lists these warning signs:
| Feature | Legitimate Credit Organization | Credit Repair Scam |
|---|---|---|
| Upfront Fees | Never charges fees before services are fully performed (banned under CROA). | Demands upfront payment or retainer before doing any credit repair work. |
| Guarantees | Offers realistic expectations; cannot guarantee specific point increases or removals. | Guarantees to erase accurate negative items or raise score by 100+ points. |
| Legal Disclosures | Provides written contract & discloses your free DIY dispute rights under FCRA. | Fails to provide a written contract or tells you NOT to contact credit bureaus directly. |
| New Identity / CPNs | Works with your existing, legitimate SSN and official credit file. | Advises applying for a CPN (Credit Privacy Number) or EIN to start a 'new credit file'. |
| Dispute Accuracy | Disputes only genuinely inaccurate, obsolete, or unverified account details. | Disputes all items without checking if they're right, encourages false statements, or fabricates disputes. |
| Cancellation Right | Provides a mandatory 3-day right to cancel the contract without any penalty. | Locks you into non-refundable contracts without cancellation rights. |
What Are Your Rights Under CROA?
The Credit Repair Organizations Act (CROA, 15 U.S.C. § 1679) strictly regulates the credit repair industry. By law, any credit repair provider must follow these CROA provisions:
- Strict Advance Fee Prohibition (15 U.S.C. § 1679b(b)): A company cannot ask for or take your money until it has actually finished the credit repair work it promised.
- Mandatory Written Contract (15 U.S.C. § 1679d): Before any work starts, the company must give you a written contract that spells out your rights, what you will pay and when.
- 3-Day Right to Cancel (15 U.S.C. § 1679e): You have the legal right to cancel the contract without any penalty or fee within three business days of signing.
- Truthful Statements Disclosure (15 U.S.C. § 1679b(a)): By law, a credit repair company cannot tell you to lie about your credit history to a bureau or a lender.
Telemarketing Protection:
If a company sells credit repair by phone, the Telemarketing Sales Rule (TSR, 16 CFR § 310) applies. The company must first show proof it delivered the results it promised. Only after that, and after six months, can it charge you.
In Nevada, credit repair organizations must register with the state's Division of Mortgage Lending under NRS 598.741 et seq. (specifically NRS 598.752). You should check their registration status online before you sign a contract.
What Credit Repair Schemes Should You Watch For?
CPN & File Segregation Fraud
Scammers sell 9-digit Credit Privacy Numbers (CPNs) or Employer Identification Numbers (EINs). They claim these numbers let you start over with no credit history. Using a CPN in place of your SSN can expose you to federal fraud charges.
Section 609 & Jamming Letters
Promising that secret legal templates force credit bureaus to delete accurate bad debt. Sending many fake dispute letters at once (known as 'jamming') will cause credit bureaus to ignore your requests.
Credit Piggybacking and Authorized User Schemes
Credit piggybacking is a risky practice, sometimes called tradeline renting. It involves paying to become an authorized user on someone else's credit card in hopes that their positive credit history will improve your score.
The FTC has repeatedly pursued companies that sell this service, both for charging illegal upfront fees and for promising score increases that did not happen. It may not improve your score the way sellers promise, so paying for a rented tradeline can leave you with little or nothing to show for the money.
What to Do If You Have Been Scammed
These operations are built by experts to trick people. Here is exactly what you need to do right now to stop them from taking more of your money:
- Stop All Recurring Payments: Cancel subscriptions immediately and notify your bank or card issuer to place a stop payment or block further charges.
- Dispute Credit Card Charges: Under the Fair Credit Billing Act, you have 60 days to ask your card company for a chargeback if the company never did the work or lied to you.
- Report to Federal Authorities: File official complaints with the FTC (ReportFraud.ftc.gov) and the CFPB. Filing an official report creates a formal paper trail that your bank or credit card company can use to support your fraud claim.
- Notify State Attorney General: File a consumer complaint with your state Attorney General's consumer protection office. This lets local regulators know about the fraud.
How to Repair Your Credit for Free (DIY Credit Repair)
You never need to pay a credit repair company to fix mistakes on your credit report. Under the Fair Credit Reporting Act (FCRA), follow these 3 simple steps for free:
- Request Free Reports: Download your free credit reports from Equifax, Experian, and TransUnion at AnnualCreditReport.com.
- Find Mistakes: Look for wrong balances, debts that belong to someone else, incorrect late payments, or old accounts that should no longer be on your report.
- Dispute Directly with Bureaus: Send a dispute online or by mail to the credit bureau showing the error. By law, the bureau has to investigate your claim and send you an answer, usually within 30 days.
If high debt is dragging down your credit score, you have safe options to handle it. You can talk to a non-profit counselor to see if debt consolidation or settlement makes sense for your budget.
Call/Text: (800) 332-8913 or request a Free Consultation online.
Frequently Asked Questions About Credit Repair Scams
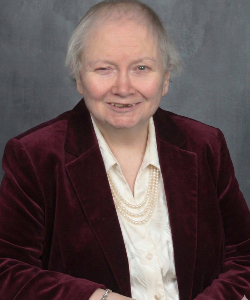
Loretta Kilday
Debt Relief Specialist & Spokesperson, DebtCC
Loretta Kilday, Esq., is an accomplished litigator and transactional attorney with more than 30 years of experience across debt collection, bankruptcy, and related matters. DebtConsolidationCare features her as its spokesperson and public voice. She has also trained and mentored junior attorneys and associates. She earned her J.D. from DePaul University College of Law and a B.S. in Finance from DePaul University.
- Loretta Kilday
ON THIS PAGE
Free debt evaluation
See your debt relief options in 60 seconds. No fees, no obligation.
Start now →Secure & confidential
KEEP READING
Related guides
Not sure if a credit offer is legitimate?
Get a free, confidential evaluation from non-profit debt specialists before paying any company.