
When Debt May Make Sense Again
Most people are taught to avoid debt at all costs, but that advice is overly simplistic. The right question is not whether debt is always bad—the better question is whether borrowing solves a problem that matters enough to justify the cost.
If borrowing helps prevent a major loss, improves your future earning power, or secures an asset with lasting value, it may be worth considering. If it only supports short-term lifestyle spending, it usually is not.
Understand Good Debt Versus Bad Debt
Good debt is borrowing that has a realistic probability of creating positive value or income over time. Bad debt usually funds transient consumption that fades quickly while payment obligations continue.
Good Debt Characteristics
- • Finances income-generating assets (education, business)
- • Secures appreciating property (primary real estate)
- • Low, fixed interest rates with manageable monthly terms
Bad Debt Red Flags
- • High-interest credit card charges for lifestyle spending
- • Loans for rapidly depreciating consumer items
- • Borrowing to cover recurring, unmanaged overspending
Medical or Family Emergencies
Some emergencies cannot wait for savings to catch up. A serious medical procedure, urgent home repair, or family crisis may force you to borrow if emergency reserves are exhausted.
In these cases, your goal is damage control: compare financing terms, negotiate medical payment plans with hospitals, avoid high-cost payday loans, and choose the shortest realistic repayment timeline.
Education or Skills That Improve Income
Borrowing for college degrees, professional certifications, or specialized trade skills can make financial sense when the expected income return is clear and the overall loan balance remains manageable.
Before signing a loan agreement, calculate the expected monthly payment against your projected entry-level salary boost. If the salary increase easily covers loan servicing with room to spare, borrowing is a justified investment.
A Home or Business That Builds Value
Taking on a mortgage for a primary home or financing capital equipment for a viable small business connects debt directly to long-term equity.
Ensure your cash flow can comfortably absorb loan payments even during economic downturns or slow business quarters. Maintain an emergency cushion alongside debt obligations.
Using Debt to Stabilize Income
Short-term financing can sometimes bridge a temporary gap—such as repairing a work vehicle to keep your job or funding inventory for immediate client delivery.
If borrowing preserves or restores your primary earning capability, it serves a strategic purpose. If borrowing only delays an inevitable budget deficit, it creates added risk.
Rules Before You Borrow Again
Before taking on new debt, follow these four golden rules:
- Define the purpose in one sentence: State exactly what problem the loan solves.
- Calculate total borrowing cost: Factoring in interest, fees, and monthly impact on your budget.
- Define your exit strategy: Map out exact monthly payments and target payoff date.
- Shop multiple lenders: Compare APR rates, origination fees, and prepayment terms.
Final Thoughts & Conclusion
Getting back into debt is worth it only when the expected financial or life outcome is measurably stronger than the borrowing cost. Whether protecting your health, boosting career earnings, or building durable home equity, intentional borrowing supports your long-term plan.
If debt does not yield measurable future value, wait, build savings, and pursue a cash-funded alternative.
Need Advice on Managing Existing Debt?
Speak with a DebtCC debt relief specialist to evaluate consolidation options, lower interest rates, and create a payoff plan.
Get Free ConsultationRecent & Important Articles
 Debt Strategy
Can You Pay Off Debts With Debt?
See when debt consolidation or balance transfers can help and when they can make things worse.
 Debt Education
What Fuels the Debt Industry?
Learn why people fall back into debt and what financial habits keep the cycle going.
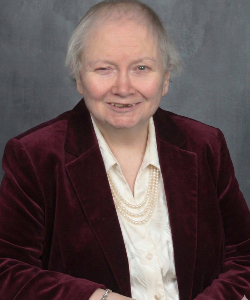
Loretta Kilday, Esq.
Debt Relief Specialist & Spokesperson, DebtCC
Loretta Kilday, Esq., is an accomplished litigator and transactional attorney with more than 30 years of experience across consumer finance, debt collection, and credit management. DebtConsolidationCare features her as its spokesperson and public voice.