Mastering Debt Negotiation Techniques
Learn what debt negotiation is, when it makes sense, and how the full process works from counseling to final settlement.
By Loretta Kilday, Debt Relief Specialist & Spokesperson
• Reviewed by the DebtCC Editorial Team
KEY TAKEAWAYS
- Debt negotiation can lower your total balance and reduce monthly financial pressure.
- Communication with creditors is handled professionally once you enroll in a structured program.
- Settlement terms should always be confirmed in writing before making any payments.
- Be aware of potential credit score impact and IRS tax considerations for forgiven debt amounts.
Debt negotiation is a strategic process where you or a representative negotiate directly with creditors or collection agencies to settle your debt for less than the full balance owed. Understand which debts qualify, how the process unfolds, and what to keep in mind regarding your credit score and taxes.
What Debts Can Be Negotiated?
Common account types that are frequently considered for debt negotiation include:
Step-by-Step Negotiation Flow
Select each phase below to preview what happens and why it matters:
Debt counseling
A counselor reviews your income, debt load, and hardship status to confirm whether negotiation is appropriate.
When Should You Consider Negotiation?
These are common indicators that debt negotiation may be an appropriate fit for your situation:
You have missed payments for 3 months or more
You are in hardship due to job loss or medical issues
Creditors are threatening legal action
The account is with collections and calls are frequent
Consolidation is not working for your situation
You are considering bankruptcy as the only option
Benefits and Trade-Offs
Understanding both sides of debt negotiation helps you make an informed decision:
- Potentially lower total balance and monthly pressure
- Possible reduction in collection harassment
- Credit score can drop during delinquency and settlement
- Forgiven debt may be treated as taxable income
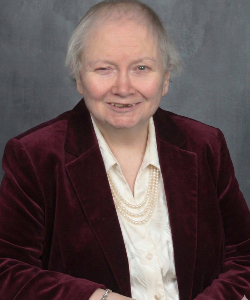
Loretta Kilday
Debt Relief Specialist & Spokesperson, DebtCC
Loretta Kilday, Esq., is an accomplished litigator and transactional attorney with more than 30 years of experience across debt collection, bankruptcy, and related matters. DebtConsolidationCare features her as its spokesperson and public voice. She has also trained and mentored junior attorneys and associates. She earned her J.D. from DePaul University College of Law and a B.S. in Finance from DePaul University.
- Loretta Kilday
ON THIS PAGE
Free debt evaluation
See your options in 60 seconds. No fees, no obligation.
Start now →Secure & confidential
KEEP READING
Related guides
DEBT RELIEF
When Should You Consider Debt Relief?
9 min read
CONSOLIDATION
Debt Consolidation: Your Complete Guide
7 min read
KNOW YOUR OPTIONS
How to Choose the Right Debt Solution for You
8 min read
Not sure which solution is right?
Get a free, no-obligation assessment. Our experts can review your situation and recommend the best path to financial freedom.