
What Is a Personal Loan in Default?
When taking out a personal loan or debt consolidation loan, borrowers sign a binding agreement promising regular monthly repayments. If you fail to make payments for 30 to 90 consecutive days, your account is officially declared in default.
While missing a payment by a few days results in a late fee (typically $15 to $40), exceeding 30 days past due triggers official delinquency reporting to Equifax, Experian, and TransUnion.
Credit Score Consequences
A single 30-day delinquency can drop your FICO credit score by 50 to 100 points. Default records remain on your credit history for up to 7 years, significantly harming your ability to qualify for future loans or credit cards.
What Happens When You Default?
When a personal loan enters default, lenders initiate a sequence of recovery actions:
1. Internal Collections & Third-Party Debt Buyers
Initially, the lender's internal collection team will call and write to demand payment. If unpaid past 120–180 days, lenders frequently sell the debt to third-party collection agencies for pennies on the dollar.
2. Accrual of Extra Interest & Collection Fees
Defaulting triggers penalty APR interest rates and collection processing fees, expanding your total balance significantly.
3. Potential Legal Lawsuits & Wage Garnishment
Debt buyers or original lenders may file civil lawsuits. If a default judgment is issued in court, creditors may obtain court orders for wage garnishment or bank account levies.
Actions to Take If You Default on a Loan
If your personal loan is delinquent or in default, taking active steps immediately prevents escalated legal and financial damages:
Contact Your Lender Early
Request temporary hardship deferment, payment pauses, or reduced interest terms before default is officially reported.
Work With Accredited Credit Counselors
Non-profit credit counselors can help structure a Debt Management Plan (DMP) to lower monthly payments.
Consult an Attorney If Sued
If served with a court summons, consult a consumer defense attorney and respond promptly to prevent default judgments.
Explore Debt Settlement
Negotiate a lump-sum settlement with debt buyers to settle the account for less than the full balance.
Understanding Your Rights Under FDCPA
Federal law protects consumers from predatory or illegal debt collection practices under the Fair Debt Collection Practices Act (FDCPA):
Key FDCPA Borrower Rights:
- ✓ No Harassment: Debt collectors cannot call before 8 AM or after 9 PM, use obscene language, or threaten arrest.
- ✓ Written Debt Validation: Collectors must send written validation stating the exact debt amount and original creditor within 5 days of initial contact.
- ✓ Right to Cease Communication: You can submit a written cease-and-desist letter requesting collectors stop contacting you directly.
- ✓ CFPB Complaints: Violations can be reported directly to the Consumer Financial Protection Bureau (CFPB) and your state Attorney General.
Consolidation & Refinancing Options
If you are struggling with high interest rates on a personal loan but have not yet defaulted, refinancing into a loan with longer terms or lower APRs can reduce your required monthly payment.
Applying for refinancing early—before missed payments damage your credit score—is essential to secure loan approval from new lenders.
Special Relief & Forbearance Programs
Many major online lenders and banks (including Best Egg, LendingClub, Discover, Upstart, and OneMain Financial) offer internal hardship programs for qualifying borrowers facing job loss, illness, or emergency financial strain.
Hardship programs may offer 3 to 6 months of reduced monthly payments, interest rate reductions, or temporary payment pauses.
Summary & Key Takeaways
A personal loan default is a serious financial setback, but it can be resolved with proactive communication, legal awareness, and structured repayment solutions. Face the issue directly, know your FDCPA rights, and explore lender hardship programs or debt relief options early.
Recent & Important Articles
 Relationships
How to Overcome Financial Infidelity in Relationships
Learn how to rebuild financial trust and create healthy money habits in your relationship.
 Debt Strategy
Are You Paying Off Debt The Right Way?
Questions and strategies to build a sustainable debt payoff plan and protect your credit score.
 Savings
Why Emergency Funds Are Crucial for Financial Resilience
Learn how to build, maintain, and structure a high-yield liquid emergency fund for financial shocks.
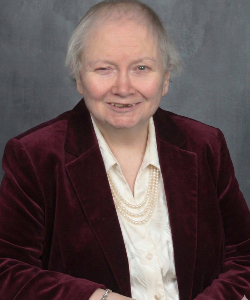
Loretta Kilday, Esq.
Debt Relief Specialist & Spokesperson, DebtCC
Loretta Kilday, Esq., is an accomplished litigator and transactional attorney with more than 30 years of experience across consumer finance, debt collection, and credit management. DebtConsolidationCare features her as its spokesperson and public voice.