
In a world dominated by contactless taps, digital wallets, and rewards points, the battle between "plastics" (credit & debit cards) and traditional "greenbacks" (paper currency & cash) shapes household financial health. Choosing how you pay impacts not just convenience, but spending volume, debt risk, and psychological discipline.
1. The Psychology of Paying: Pain of Cash vs. Convenience of Plastic
Behavioral economists frequently study the phenomenon known as the "Pain of Paying." When you physically hand over paper bills (greenbacks) to purchase an item, your brain experiences an immediate psychological loss.
MIT Behavioral Study Insight
Famous experiments at MIT revealed that buyers offered sporting tickets were willing to bid up to 83% more when paying with a credit card compared to buyers restricted to physical cash.
Plastic cards decouple the pleasure of acquiring goods from the pain of parting with money. Because the bill arrives 30 days later, swiping plastic feels frictionless—often encouraging impulse buys that greenbacks naturally prevent.
2. Overspending Risks: Why Credit Cards Encourage Higher Basket Sizes
Retailers and fast-food chains love plastic payments because average transaction sizes increase significantly.
Plastic Swipes
Cardholders are more likely to add premium upgrades, dessert items, or extra accessories because card limits obscure real-time bank balances.
Cash Greenbacks
When your wallet only contains three $20 bills, your spending ceiling is physically hard-capped at $60.
3. Rewards vs. Interest: The Math Behind Credit Card Cash-Back
Credit card marketing heavily emphasizes rewards: 2% cash back, airline miles, and sign-up bonuses. However, rewards are only lucrative if you pay your monthly statement balance in full every single cycle.
The Cash-Back vs. APR Math
- Earning 2% cash-back on a $1,000 purchase yields $20 in rewards.
- Carrying that $1,000 balance for one year at a 22% variable APR costs $220 in interest charges.
- Net loss: -$200. Carrying a balance turns credit card rewards into negative value.
4. Fraud Protection & Convenience: Where Plastics Outshine Cash
Despite spending risks, plastic credit cards offer major security advantages over paper greenbacks:
- Zero Fraud Liability: Under federal law (Regulation Z / FCRA), consumer liability for unauthorized credit card charges is capped at $50, and major card issuers offer 100% zero liability coverage.
- Lost Currency Risk: Stolen or misplaced cash greenbacks cannot be recovered or tracked once lost.
- Travel & Rental Benefits: Credit cards provide rental car insurance, dispute protection, and hotel hold flexibility impossible with paper currency.
5. The Cash Envelope System: When Greenbacks Make Sense
For households struggling with credit card debt or monthly overspending, transitioning variable categories (groceries, dining out, entertainment) to paper cash greenbacks restores financial control.
The popular Cash Envelope System allocates physical cash into categorized envelopes at the start of each month. When an envelope is empty, spending in that category stops immediately until the next paycheck.
Conclusion & Smart Spending Guidelines
Neither plastics nor greenbacks are inherently evil or perfect. The optimal financial strategy uses a hybrid model: leverage credit card plastics for recurring fixed bills, travel, and online purchases paid off in full monthly, while using cash greenbacks for discretionary categories prone to overspending.
Recent & Important Articles
 Banking & Credit
Stop Using Debit Cards for Daily Purchases
Discover why swiping debit cards exposes your primary checking account to bank holds, fraud risks, and limited recovery.
 Banking
The Sneakiest Bank Fees and How to Avoid Them
Uncover hidden bank fees—from monthly maintenance charges to overdraft penalties—and learn how to eliminate them.
 Credit Cards
9 Rules for Credit Card Newbies to Build Healthy Spending
Master essential credit card rules to build strong credit scores, earn rewards, and avoid costly interest traps.
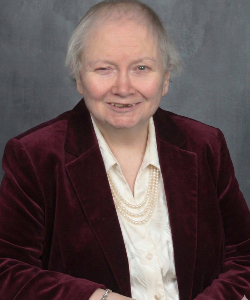
Loretta Kilday, Esq.
Debt Relief Specialist & Spokesperson, DebtCC
Loretta Kilday, Esq., is an accomplished litigator and transactional attorney with more than 30 years of experience across consumer finance, debt collection, and credit management. DebtConsolidationCare features her as its spokesperson and public voice.