
1. Why payday loans seem easy
Payday loans can look like an easy fix when cash is tight and emergency expenses pop up. Approval is fast, credit checks are minimal, and money is deposited into your checking account within hours.
That speed and convenience is precisely what makes payday lending a multi-billion dollar market. But speed often masks severe costs, hidden fees, and predatory terms that trap consumers in long-term debt cycles.
2. Why avoid payday loans (9 Key Risks)
1Giving out personal information to unverified lenders
Online application forms often request sensitive personal, employment, and banking details. Sharing this with unverified online lenders increases identity theft and data exposure risk.
2Hidden charges and stacking origination fees
Lenders commonly charge steep fees for every $100 borrowed. These charges stack quickly, significantly inflating the actual cost of short-term borrowing.
3Triple-digit annual percentage rates (APR)
Payday loan interest rates frequently climb to 300%–400% APR or higher, dwarfing typical credit card interest rates.
4Short 14-day repayment terms
Borrowers are usually required to repay the full principal plus fees within two weeks. Most borrowers cannot afford full repayment in 14 days and are forced into costly rollovers.
5Automatic bank account withdrawals
Pre-authorized ACH access allows lenders to drain checking accounts directly, triggering NSF overdraft fees and bounced checks.
6High vulnerability to chronic debt traps
Borrowers routinely take a new payday loan to pay off an existing one, locking themselves into an endless cycle of fees and renewals.
7Difficulty escaping the debt cycle
Once balances outpace income, aggressive collection tactics, harassment, and credit damage follow quickly.
8Aggressive or illegal collection harassment
Unscrupulous collection agencies use abusive tactics. Consumers should know their rights under the FDCPA and report illegal threats to the FTC.
9Payday loan legality varies by state
Payday lending is banned or heavily capped in over 18 states. Some offshore or tribal lenders falsely claim immunity from state consumer protection laws.
3. Alternatives to payday loans
Before taking on 400% APR payday loans, consider safer alternatives that offer lower rates and manageable repayment schedules:
- Payday Alternative Loans (PALs) from federal credit unions
- Structured payment plans or hardship extensions with current creditors
- Payroll advances or emergency assistance programs from employers
- Non-profit consumer credit counseling services
- Overdraft protection options through primary credit unions
- Small personal installment loans with fixed rates
- Military relief society emergency loans for service members
- Structured debt consolidation or settlement programs
Trapped in High-Interest Payday Debt?
Speak with our debt relief specialists to consolidate multiple payday loans into one manageable monthly payment and stop predatory interest cycles.
Recent & Important Articles
Payday LoansWhat Are the Alternatives to Payday Loans?
Explore 7 safer, low-cost alternatives to payday loans including PALs, credit union loans, and debt relief.
 Debt Help
Steps to Deal with Payday Loan Problems
A practical action plan to regain control when high-interest debt starts to spiral.
 Tax & Retirement
Retirees: Making Tax Season Simple & Stress-Free
Navigate tax season with confidence. Discover essential tax tips, deductions, credits, and strategies.
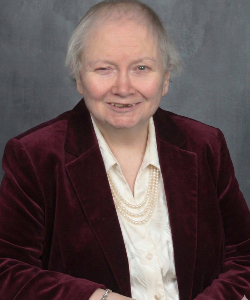
Loretta Kilday, Esq.
Debt Relief Specialist & Spokesperson, DebtCC
Loretta Kilday, Esq., is an accomplished litigator and transactional attorney with more than 30 years of experience across consumer finance, debt collection, and credit management. DebtConsolidationCare features her as its spokesperson and public voice.